Wallet screening risk scores explained: what they mean and when they get it wrong
Published: Last reviewed: How we edit
Analytics tools rate a crypto address by tracing its past connections to other addresses and services. Scores are usually sorted into low, medium and high, often shown as green, amber and red. These reflect how near the address sits to things like scams, mixers or sanctioned entities. Treat the score as an estimate, never a verdict. It can be wrong, or simply outdated.
Got a question about your case? Ask us here:
What screening does
Exchanges, banks and payment firms screen crypto addresses before dealing with them. The software checks where an address got its funds, where it sent them, and which services it used along the way.
You get back a score or a label. A company then decides: accept the deposit, hold the withdrawal, or ask you for more details.
What the colours and categories mean
Each provider builds its own scale. Numbers and names differ, and there is no shared standard. Most tools still follow the same basic idea.
- Green or low: no solid connection to risky categories showed up, or any connection sits far away.
- Amber or medium: some ties to categories that call for a closer check, like gambling, certain exchanges or high-risk regions.
- Red or high: a close or direct tie to categories like sanctioned entities, scams, ransomware, darknet markets or mixers.
- Category labels: the tool can name the exposure type, for instance mixer, fraud or sanctions, and can show how many hops away it sits.
- Direct versus indirect exposure: a direct connection normally gets taken more seriously than one sitting several hops away.
Why a score can misfire
These tools run on patterns and probabilities, so mistakes happen. The most common one is indirect exposure. Your address got funds from someone who had gotten funds from a flagged source, and the score picks up that distant connection even though you had no way to see it coming.
There is also clustering. Software lumps together addresses it thinks share one owner, and now and then it lumps them the wrong way. Labels can go stale too, since a service can change hands or an address can be reused once the original risk is gone.
Providers can also disagree about the same address. One tool rates it high and another rates it low. That mismatch is a good reason to request a closer review.
What happens when a score leads to a block
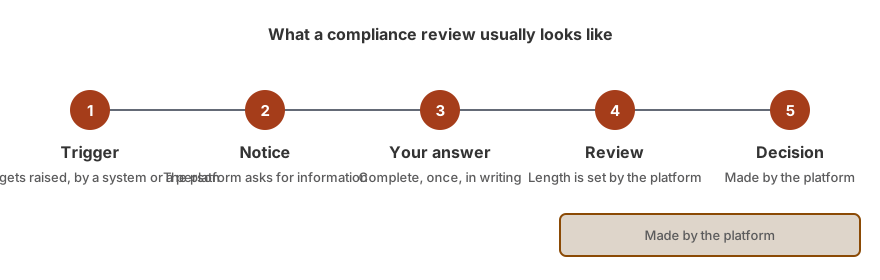
If the score looks high, the company may freeze your deposit or limit your account while staff review it. Expect requests for proof of funds, ID documents, or a written explanation of the transaction.
Companies rarely admit the score caused it. Usually they just say your account is under review. So ask directly which transaction or address triggered the alert. That is the question worth pushing.
How to push back on a score
Specific challenges work. Vague ones do not. Point to the exact address and transaction, then attach a short explanation with documents behind it.
- Ask which address and which transaction set off the alert.
- Build a transaction history showing how the money got to you and what it was for.
- Include evidence of where the funds came from: exchange records, receipts, or a bank statement.
- Ask the company to take a second look at the alert, or have its provider run the check again.
- Put every reply in writing, and use only the company's official channel.
Where we step in
We review your case at no cost. Independent specialists look at the address history, explain what the score likely reflects, and help you build a clear challenge. Here is the hard part: we cannot alter a score or make any company accept your challenge. And nobody here will ever ask for your seed phrase, private keys, or passwords.
Frequently Asked Questions
If my wallet gets a red score, does that prove I did something wrong?
No. It only means the software spotted a link to a risky category. That link can be old or secondhand. A person then judges whether it actually matters, and clear documents plus a plain explanation usually resolve it.
Can I look up my own wallet score?
A few analytics firms run limited free checks. Others sell reports only to businesses. Tools do not agree with each other, so treat any single score as a hint, never the final word.
Can a wallet score be taken off?
Providers will revise labels when you hand over solid evidence, but they owe you nothing. In practice the real goal is usually to satisfy the company holding your funds, not to fix the score itself.
Why did my exchange take the deposit, then freeze it later?
Screening can run again as fresh data comes in. A label may change after your deposit lands, which can put already accepted funds under review. The exchange may then demand documents from you.
How we can help
- Wallet screening flags and risk disputes. Flagged high risk by screening tools: document the funds path and dispute it.
- Blockchain analytics report, explained plainly. Traced transaction evidence for a source-of-funds report, built for compliance review.
- Proof of funds and wealth origin packs. Prepare a clean source of funds and source of wealth pack that exchanges, banks and processors will accept.
- Who froze my crypto? A freeze diagnosis. Name who froze your funds, then see what can realistically be done.
Everything on this page is general information. It is not legal advice.